Everyday Systems · Shopping & everyday services
How a payment moves between US banks
Follow a paycheck and a bill through the batch network behind US direct deposits and bill payments, see when the money really moves, and learn what changed when instant payments arrived in 2023.
What you will learn
- Tell a credit transfer from a debit transfer by who starts it
- Sort a familiar payment into one type or the other
- Name what an ACH operator does between the sending and receiving institutions
- Explain how a payment is handled when the two institutions use different operators
Lesson 1 of 4 · 5 min
Your paycheck and your power bill share one network
In 2025, one US network carried 35.2 billion payments worth $93 trillion. It delivered paychecks, tax refunds and Social Security benefits, and it collected mortgage and utility payments. Most people who rely on it couldn't tell you its name.
It's the automated clearinghouse, or ACH. Banks and credit unions use it to send each other batches of electronic payments. A batch is a file of many payments gathered together, so no payment travels alone.
Every payment in those files runs in one of two directions. Most of what follows depends on which.
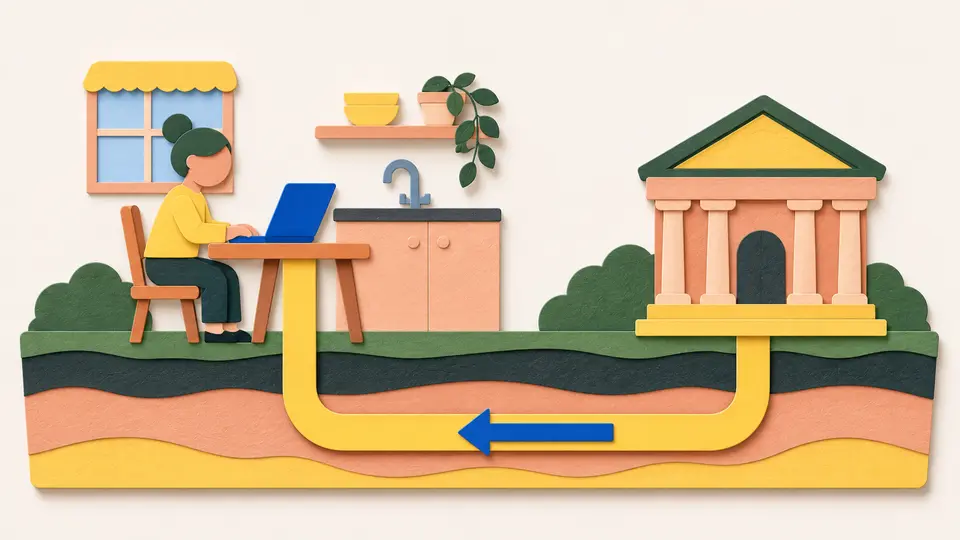
A credit transfer is a push. The party with the money tells its bank to send it. Your employer does this before each payday, with a file that lists every employee's account and amount. Payroll, Social Security benefits and tax refunds all arrive this way, as direct deposits.
A debit transfer is a pull. The party that's owed the money starts the collection, from an account it has been authorized to draw on. Mortgage payments and utility bills taken by direct debit are typical.
Either way, the money ends up with the party that was owed. What differs is who starts the instruction.
The network exists because of paper. In 1968, a group of California bankers worried that the growing volume of paper checks would outrun the equipment that cleared them. That worry led to the first ACH association in 1972.
At first the network carried mostly recurring payments. The US Air Force was the first employer in the country to pay its people by direct deposit.
Today it's also used heavily for one-time debits. Those include checks converted into electronic payments, and payments made by phone or over the internet, which became possible in 2001. So a payment you type into a website may be an ACH debit underneath.
Batching sets the pace. A bank doesn't send your payment the moment you make it. The payment joins a file, and the file goes out at a set time.
That's efficient, and it's why ACH payments historically haven't been instant. Each one waits for its file, and the network keeps to banking days. A payday that falls on a weekend is paid the Friday before. A bill due on a weekend is collected the next business day.
The wait is usually short. Nacha, the body that writes the network's rules, estimates that 80% of ACH payments are complete within one banking day.
So the paycheck and the power bill ride the same network in opposite directions. Your employer pushes the pay. The utility pulls the bill, with your authorization. Both wait in a batch, which is why neither is instant.
Lessons in this topic
Your paycheck and your power bill share one network
Paychecks, benefits and many bills travel over one US network. See what it is, why it moves payments in batches, and how a push differs from a pull.
When the money actually moves between banks
An operator sits between the two banks in every ACH payment. See its four steps, and why the last one, settlement, is when the money moves.
FedNow and the business day that never ends
Since 2023, US banks have been able to settle a payment in seconds at any hour. See what FedNow is, what it isn't, and how its business day covers every day of the year.
Why instant payments need funds ready at 3 in the morning
When payments never stop, a bank's balance can run down while its usual sources of funds are closed. See how FedNow lets banks top each other up, and what else its first release included.
Three quick stories from this topic
FedNow has no app
The Federal Reserve spent $545 million on a payment system that has no app
FedNow, switched on in July 2023, lets banks settle a payment within seconds at any hour of any day. It only connects banks to each other, so the Fed says customers will probably never see its name. Each bank builds its own product on top.
A day that never ends
FedNow's business day lasts 24 hours and there's one every day of the week, weekends and holidays included. That lets end-of-day balances still be reported for each bank.
Only if both banks join
The United States has about 9,000 banks and credit unions, and each decides whether to sign up. An instant payment can only reach an account at one that has.
Why some paychecks arrive early
Some US banks pay wages early by advancing their own money before the employer's arrives
Payroll reaches a bank as a message first. The money follows later, at a step called settlement. Nacha, which writes the rules for the payroll network, says direct deposits are so routine that some banks credit the pay before settlement happens.
Message first, money second
An operator between the two banks receives the payroll file, sorts the payments and delivers the instructions. Only its last step, settlement, moves money between the banks.
Payday on a weekend
The network keeps to banking days. A payday that would fall on a weekend or holiday is paid on the Friday before.
A network born from paper checks
The network that delivers US paychecks began with bankers afraid of too many paper checks
In 1968, a group of California bankers feared that check volume would outrun the equipment that cleared it. By 1972 California had the first automated clearinghouse association. In 2025 the network carried 35.2 billion payments worth $93 trillion.
Push and pull
The network carries payments in two directions. An employer pushes pay to workers as a credit transfer. A utility pulls a bill payment from a customer as a debit transfer.
Still sent in batches
Banks send each other files of many payments at set times. That's efficient, and it's why a payment on this network waits for its file.
Sources
- Automated Clearinghouse Services, Board of Governors of the Federal Reserve System
- ACH Network Volume and Value Statistics, Nacha
- How ACH Payments Work, Nacha
- History of Nacha and the ACH Network, Nacha
- FedNow Service, Board of Governors of the Federal Reserve System
- FedNow Service: Frequently Asked Questions, Board of Governors of the Federal Reserve System
- FedNow Service: Additional Questions and Answers, Board of Governors of the Federal Reserve System