Business & Organizations · Accounting & business finance
Profit is not the same as cash
Follow a small firm through credit sales, expenses and payments to see how it can make a profit and still run short of cash.
What you will learn
- Tell revenue apart from cash received under accrual accounting.
- Explain how a profitable period can still leave a business short of cash.
- Match the income statement, balance sheet and cash-flow statement to the questions they answer.
- Tell borrowing cash apart from earning revenue.
Lesson 1 of 4 · 4 min
How a profitable job can leave a business short of cash
A design studio finishes a job and sends the customer an invoice for 2,000, payable next month. The studio will report a profit on that job this month. It may also be unable to pay its bills. Both can be true, and the reason is timing.
The studio has earned the revenue, because the work is done. The cash hasn't arrived. Until it does, the 2,000 is an account receivable, money a customer owes for work already delivered. So when does the sale count, now or when the money comes?
It depends on how the books are kept. Accrual accounting records revenue when it's earned and expenses when they're incurred, whenever the cash moves. Cash-basis accounting waits. It records nothing until money changes hands.
Take a mechanic who tunes up a car on May 29 and is paid on June 2. On accrual books that's May revenue. On cash books it's June revenue. Public companies report on the accrual basis. Some small businesses choose the cash basis because it's simpler to track.
Real contracts come with more detailed rules. A finished job with an unpaid invoice is enough to show the timing difference.
Back to the studio, which keeps accrual books. Say it also pays 1,200 in costs for the job this month. Ignoring everything else, it reports 800 of profit, the 2,000 of revenue minus 1,200 of expenses.
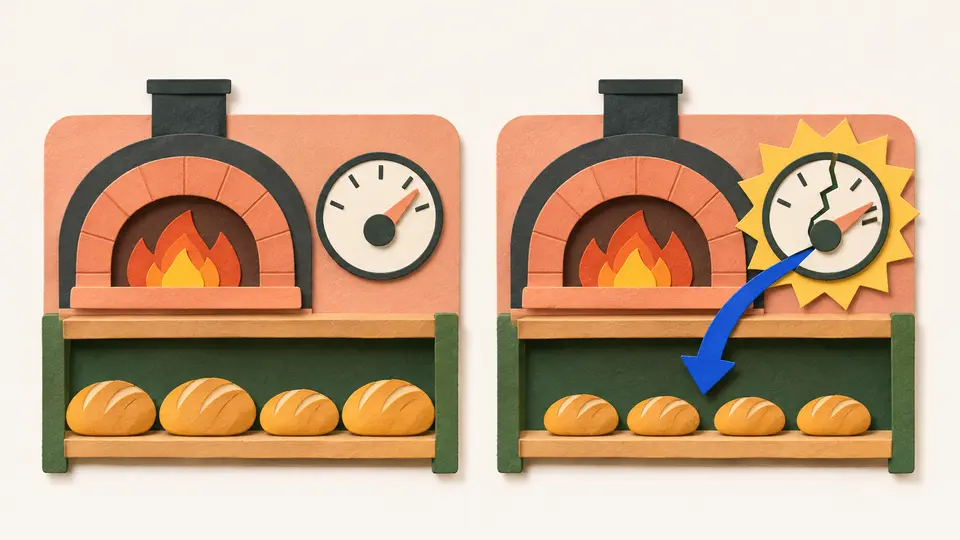
Now count only the money. Nothing has come in and 1,200 has gone out, so the job's cash flow this month is minus 1,200. Profit says the job was worth doing. Cash flow says the studio has 1,200 less in the bank today. Both are accurate, because they answer different questions.
Now say the studio started the month with only 500 in the bank. The 1,200 of bills is due, so the studio is 700 short. Pointing to the 800 profit won't help, because nobody takes a profit figure as payment.
The unpaid invoice is an asset, but it isn't money in the bank today. The studio has three ways out. It can collect cash sooner, change when it pays, or arrange funding to cover the gap. Without one of them, a profitable business misses its bills.
Try to recallA design studio invoices 2,000 for a completed job, payable next month, and pays 1,200 of costs now. How can it report a profit and still not have the money for this month's bills?
Revenue can be recognized before the customer's cash is collected, while the bills have to be paid in cash now. The receivable on its own can't pay them.
Lessons in this topic
How a profitable job can leave a business short of cash
Follow one design job from invoice to payment to see why a sale is recorded before the money arrives, and why a profit can't pay this month's bills.
What the three financial statements each tell you
Learn which question the income statement, the balance sheet and the cash-flow statement each answer, and why a loan raises cash without raising profit.
Why winning more work can drain your cash
See how doubling sales doubles the bills that come due before customers pay, and what a cash forecast has to spell out to warn you in time.
Spending that isn't an expense yet
Follow a computer purchase and a customer's advance payment, two cases where cash moves once and the profit figure catches up later.
Three quick stories from this topic
Book value isn't a price
A building's value on a company's balance sheet isn't what it would sell for
Accountants typically list a building at what it cost, minus the depreciation charged so far. A building bought for $1,000,000 and written down to $800,000 could sell for more, less or the same. The figure tracks cost used up, and nobody appraised anything.
Where book value comes from
Book value is cost minus accumulated depreciation, which is the share of the original cost already allocated to past periods. It records what has been used up, and it isn't an appraisal. The same is true of almost any asset except cash itself.
What a balance sheet can and can't tell you
A balance sheet tells you what an organization paid and how much of that cost has been expensed, which helps when judging profit. It doesn't tell you what the assets are worth on the market, so valuing a business takes other evidence.
An advance payment is a debt
Money paid to a law firm in advance sits on its books as a debt until the work is done
Accountants call it unearned revenue, and it's a liability. The firm owes the client either the work or the money back. Only as the work gets done does the payment turn into revenue, with no new cash changing hands.
The same rule at the grocery store
A grocery store that takes a 50% deposit to cater a party has unearned revenue until the party happens. Only then does the deposit count as revenue.
Why the books wait
Under accrual accounting, revenue is recorded when it's earned, whenever the cash arrives. Counting an advance as revenue would overstate profit in the month the money came in.
A sale before the money
A business records a sale on the day the work is done, even if no money has arrived
That's accrual accounting, the method public companies use. Customers buying on credit often get up to 45 days to pay, and the bills for the work come due in the meantime. So a firm can report a profit in a month when it can't cover its costs.
Follow one design job
A finished 2,000 job with 1,200 of costs can show 800 of profit. If the costs are paid this month and the customer pays next month, this month's cash flow is minus 1,200.
Keep both views
The receivable is an asset, but bills have to be paid with cash on hand. Profitability and liquidity answer different questions about the same business.
Sources
- 4.1 Explain the Concepts and Guidelines Affecting Adjusting Entries - Principles of Accounting, Volume 1: Financial Accounting | OpenStax, OpenStax, Rice University
- 2.1 Describe the Income Statement, Statement of Owner’s Equity, Balance Sheet, and Statement of Cash Flows, and How They Interrelate, OpenStax, Rice University
- 4.2 Discuss the Adjustment Process and Illustrate Common Types of Adjusting Entries - Principles of Accounting, Volume 1: Financial Accounting | OpenStax, OpenStax, Rice University